Inventory financing is business funding used to buy stock ahead of sales, typically secured by that inventory and recorded with a UCC filing. Crestford Lending, a small-business funding broker in Waterloo, Iowa, explains how partners value stock and compares the option with lines of credit and factoring, then routes requests to lending partners, which decide and set terms.
| Designed for | Goods purchased before customers buy them |
|---|---|
| Security | The inventory, recorded by a UCC filing |
| Repayment | Unit by unit as goods sell, or on set dates |
| Black Hawk County, IA retail | 463 payroll employers, 2023 (Census CBP) |
| Black Hawk County, IA wholesale | 156 payroll employers, 2023 (Census CBP) |
| Who decides | The partner valuing the stock; Crestford Lending arranges |
How inventory financing works
The partner advances money to buy goods, and those goods secure the funding. Because stock can lose value, partners rarely lend against its full cost; they lend against a portion of what they think it would fetch if it had to be sold. Fast-moving, easily resold goods support a larger share than fashion lines or custom-made parts.
Repayment either follows sales, with each unit sold paying down part of the balance, or runs on a fixed schedule like a short term loan. In both cases the partner usually records a UCC financing statement against the inventory, and sometimes against other business assets too.
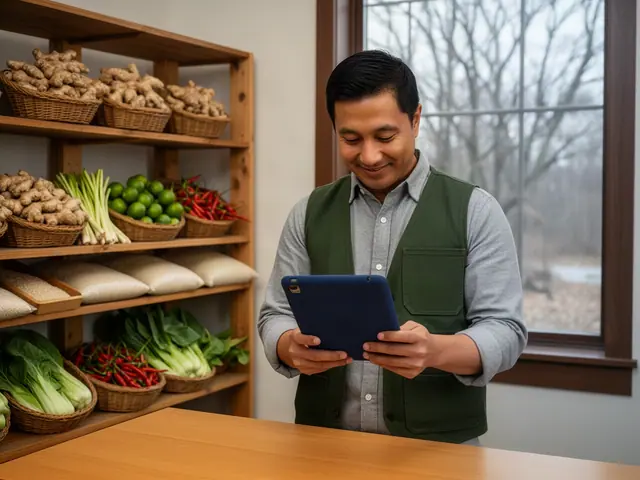
Shelves and warehouses in Black Hawk County, Iowa
Retail trade had more employer establishments than any other sector in Black Hawk County in 2023: 463, employing 9,299 people with about $290.2 million in annual payroll. Wholesalers accounted for another 156 employer establishments, with 2,800 on staff (U.S. Census Bureau, County Business Patterns 2023). Another 705 retail businesses and 123 wholesale businesses operated with no paid staff in 2024 (Nonemployer Statistics 2024), a separate count that is not added to the employer figures.
Those are the businesses most likely to have cash sitting on shelves. Funding by sector sets retail and wholesale alongside the other sectors, and how the county's employers break down shows the office ZIP's own counts.
UCC filings and what they mean for you
A UCC financing statement is a public notice that a creditor claims an interest in certain assets. With inventory financing, it tells other creditors that the stock is spoken for. That matters later: a second partner may hesitate to fund against inventory that already has a lien on it, and a blanket lien from an earlier loan can block new inventory funding altogether.
Before applying, check what is already on file. Searching Iowa UCC filings explains how owners look up liens against their own business and what to do about old ones.
Valuing stock the way a partner does
Partners look past what you paid for the goods to what they would bring if they had to be sold quickly. Finished goods with steady demand count for more than raw materials or work in progress. Expect questions about how old the stock is, how much is returned or damaged, and whether any of it is consigned rather than owned. A clean inventory report sorted by age is often the single most useful document you can send.
Floor plan financing
Floor plan financing is a specialised form of inventory funding for high-value items sold one at a time, such as vehicles, boats or large equipment. The partner pays the manufacturer for each unit, the dealer pays interest while the unit sits on the lot, and the balance for that unit is paid off when it sells. Partners usually audit the stock regularly to check that every financed unit is still there or has been paid for.
Stock loan, invoice sale or credit line
| Inventory financing | Invoice factoring | Line of credit | |
|---|---|---|---|
| What backs it | Goods on hand | Unpaid customer invoices | Business credit and often assets |
| Best for | Paying suppliers ahead of the sale | Waiting on business customers to pay | Recurring, uneven costs |
| Repayment | Per unit sold, or by calendar | Customers pay the factor | On the drawn balance |
Factoring is not one of the six routes Crestford Lending arranges, but owners often ask how it compares. If your cash is stuck in unpaid invoices rather than in stock, discuss it with your accountant. When stock purchases recur every few weeks, a business line of credit may be more flexible than separate inventory advances.
Paperwork for a stock-backed request
- A current inventory list with costs and quantities
- How quickly stock turns, ideally by product category
- Recent bank statements and sales history
- Supplier invoices or purchase orders for the stock being financed
- Any liens already filed against business assets
Equipment such as shelving, coolers or a forklift is not inventory and is financed differently; see equipment financing.
Signs inventory financing is the wrong tool
If stock is not selling, financing more of it deepens the problem. Slow-moving or obsolete goods support little funding and tie up the cash that would otherwise repay it. Clearing old stock, renegotiating supplier terms or ordering in smaller batches can come first. For the bigger picture, the six routes compared and the four steps are good next reads.
By Crestford Lending · Updated
Questions for the W 4th St broker?
Unsure of the route? Ring us, or begin online.